Wimbledon Bettor Profile: Gender, Age and Frequency Data for the UK Market
 Available in US
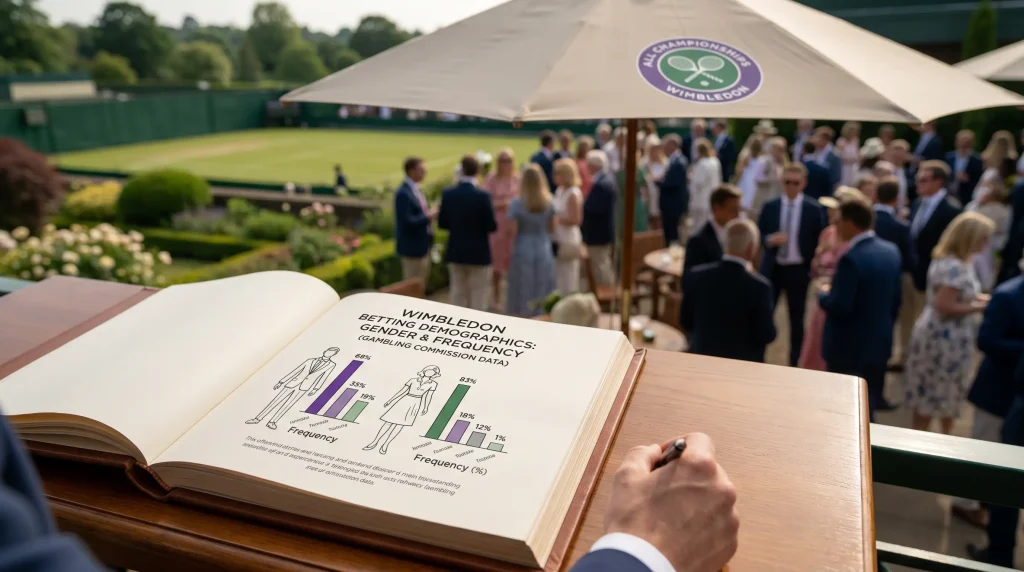
Who actually bets on Wimbledon in the UK? The question matters beyond the obvious commercial reason. If you understand who else is participating in the same markets you are, you understand where the inefficiencies are — which segments of the audience are creating pricing pressure, which ones are not, and where analytical advantage is available. The Gambling Commission’s Gambling Survey for Great Britain and the OLBG/YouGov Wimbledon survey together provide the most granular picture available of the UK Wimbledon betting population. What follows draws on both to build a precise demographic portrait — not anecdotal, not assumed, but data-anchored. Ten percent of UK adults bet online on sports, according to the most recent Gambling Commission data. The subset of that 10% who bet on Wimbledon has a specific profile that is worth understanding before you place a single bet.
Gender and Wimbledon Betting: A 15% vs. 4% Gap
The most stark demographic fact in UK sports betting is the gender gap. In Q1 2025, 15% of men placed sports bets, compared to 4% of women — a greater than three-to-one ratio. This gap is not Wimbledon-specific; it applies across all sports betting. But it shapes the Wimbledon market in ways that are concrete and visible.
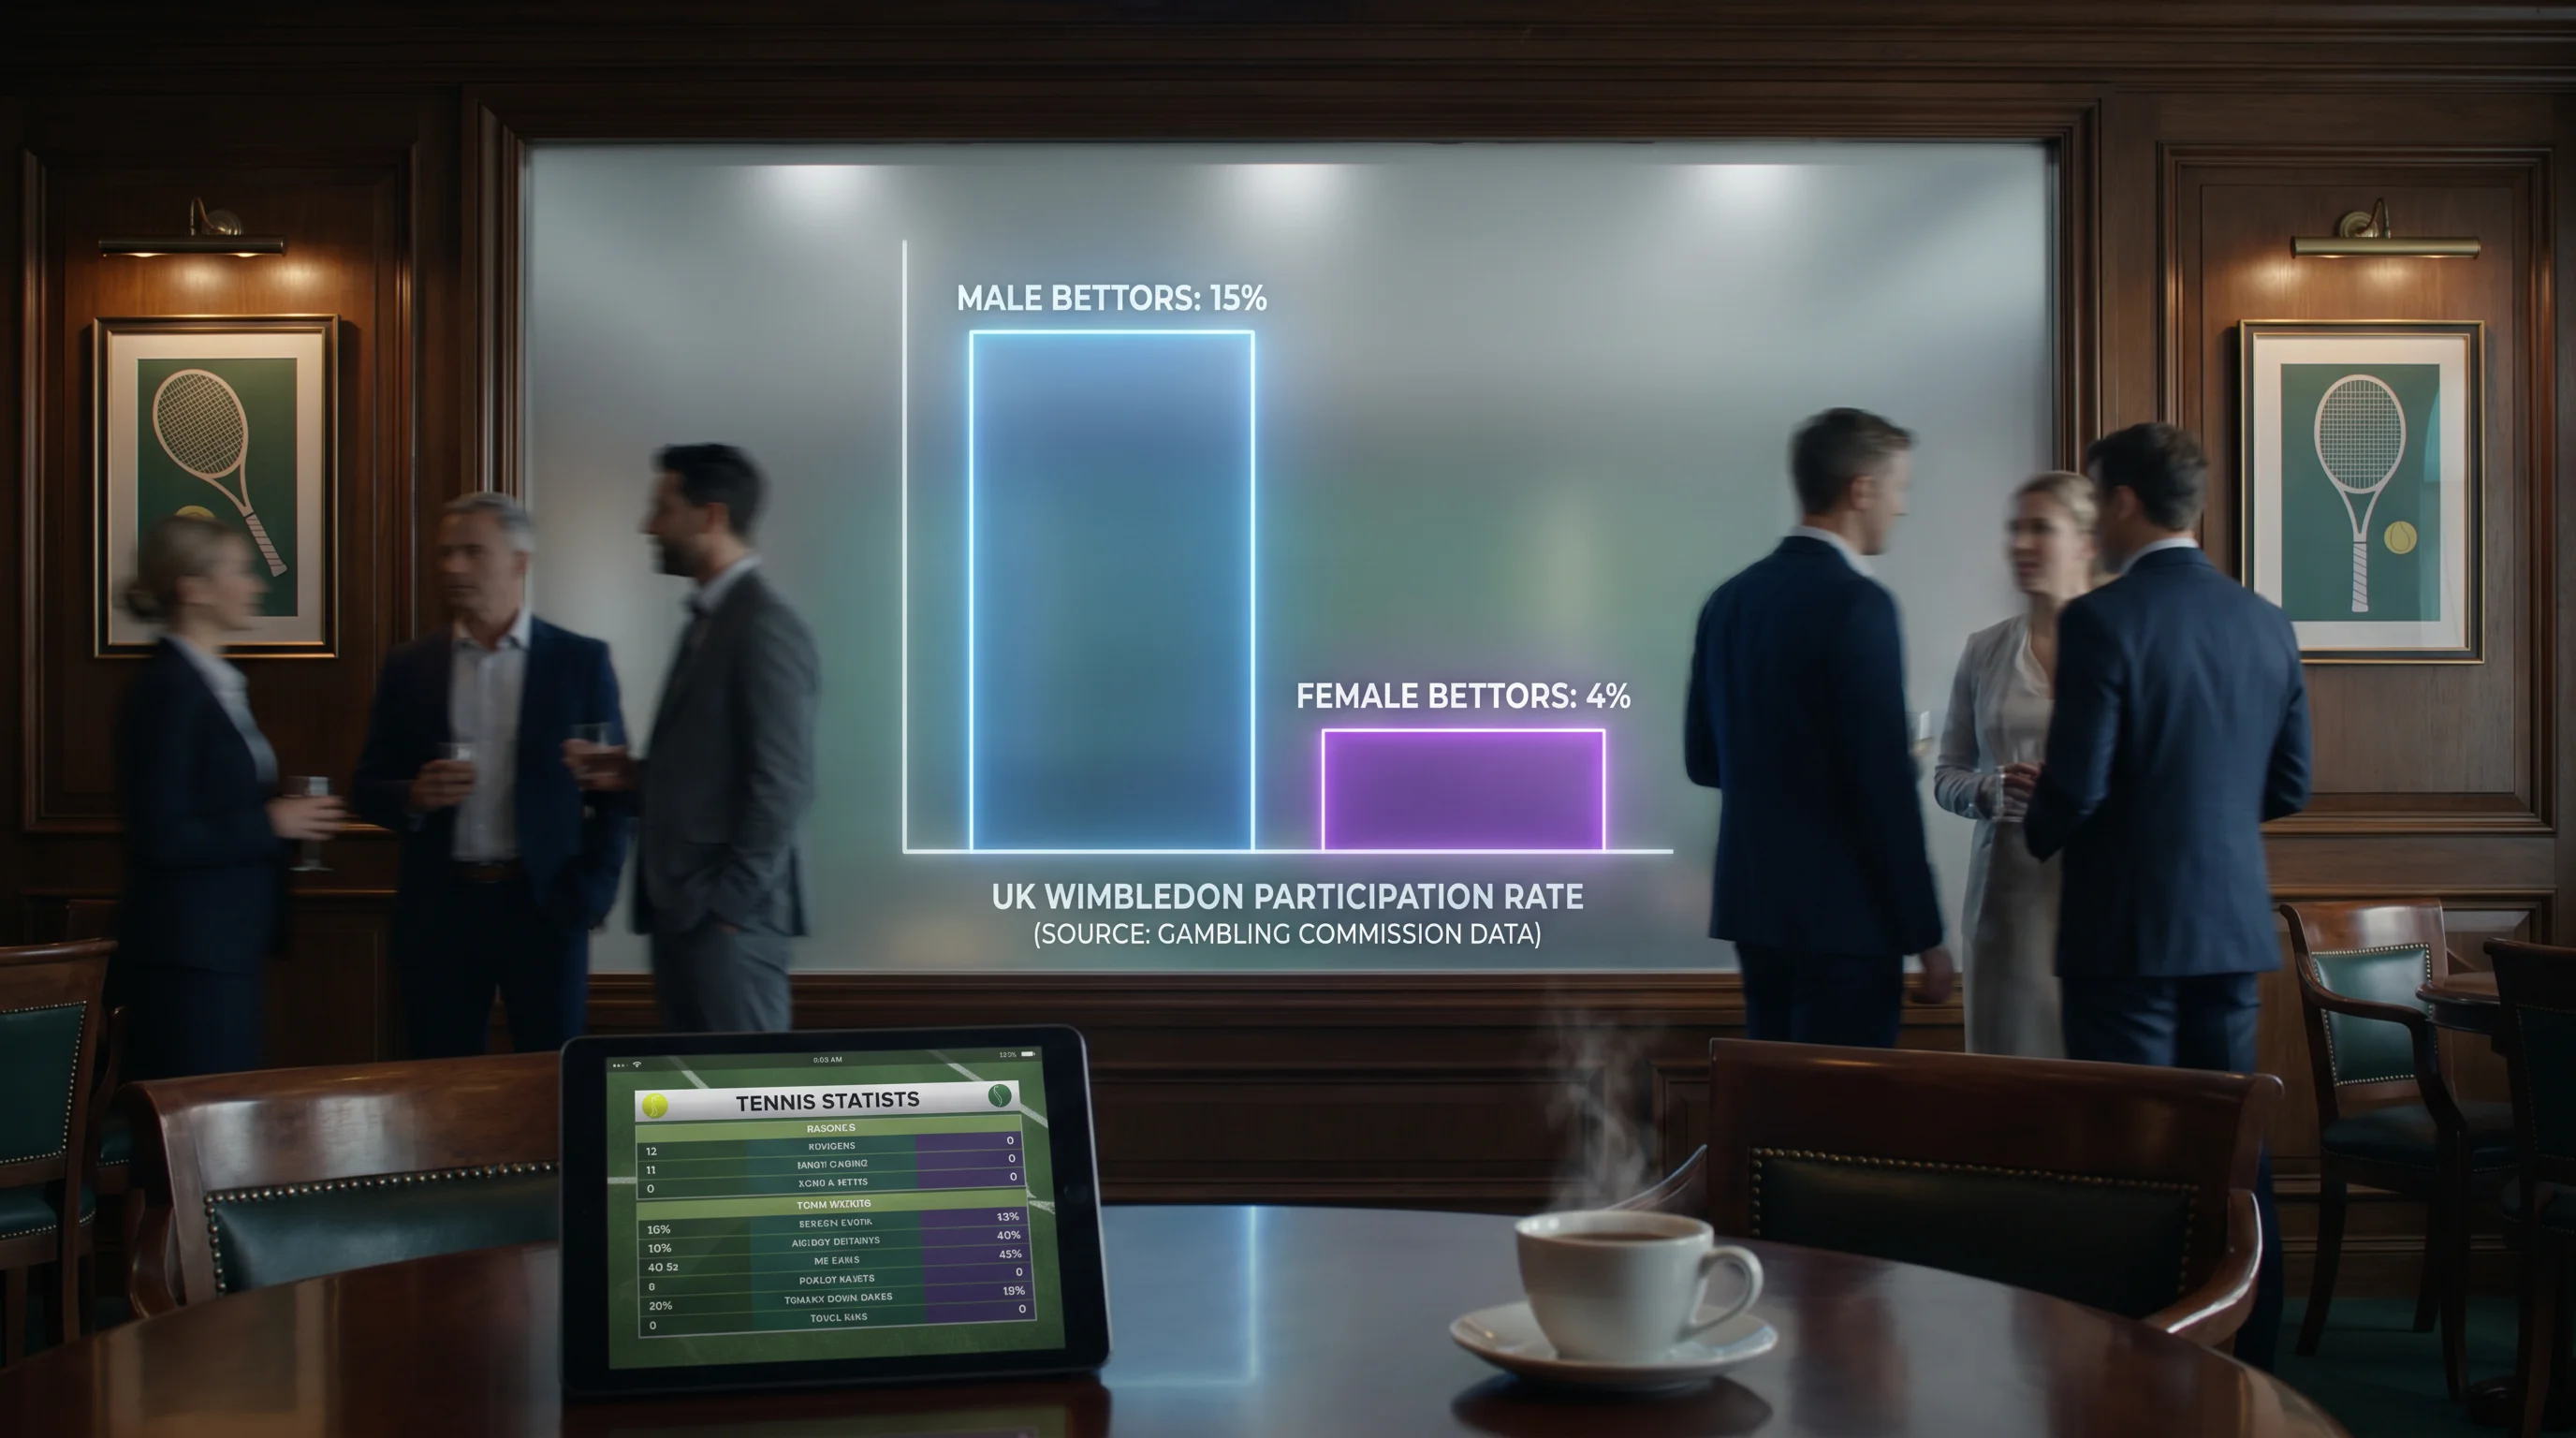
Football is the most bet sport in the UK, with 6% of all UK adults wagering on it. The male audience for football betting accounts for the large majority of that volume. Tennis — and specifically Wimbledon — sits in a different demographic position. The Wimbledon television audience is more gender-balanced than the football audience, with women representing a significant share of the 37% of UK adults who plan to watch the tournament. That watching audience does not translate proportionately into betting: the betting audience skews male, consistent with the general 15% versus 4% breakdown.
For market analysis, this demographic shape has a specific implication. The male-dominated betting audience at Wimbledon concentrates on the men’s singles — consistent with broader sports viewing patterns — which means the men’s singles outright market and first-week match betting receive disproportionate volume relative to the women’s draw. The women’s singles markets, by contrast, are set by a smaller and more analytically sophisticated audience, because they attract less casual money from the large casual-male segment. This market composition difference is one reason why experienced analysts often find more value in women’s singles betting than in the men’s equivalent, particularly in early rounds where draw quality differences between players are genuine but the market pricing is less refined.
The gender gap also influences which narrative-driven bets attract the most casual money. Domestic interest in British players has historically been stronger among male bettors in their primary sports-betting demographic than among the broader audience. When Jack Draper or another British player performs well during the grass swing, the male-heavy domestic betting audience creates a more pronounced price compression effect than would occur in a more gender-balanced market. Recognising that compression — and knowing whether it has moved a price beyond fair value — is easier when you understand the demographic mechanism producing it.
Seasonal Bettors: The 22% Who Bet Only at Grand Slams
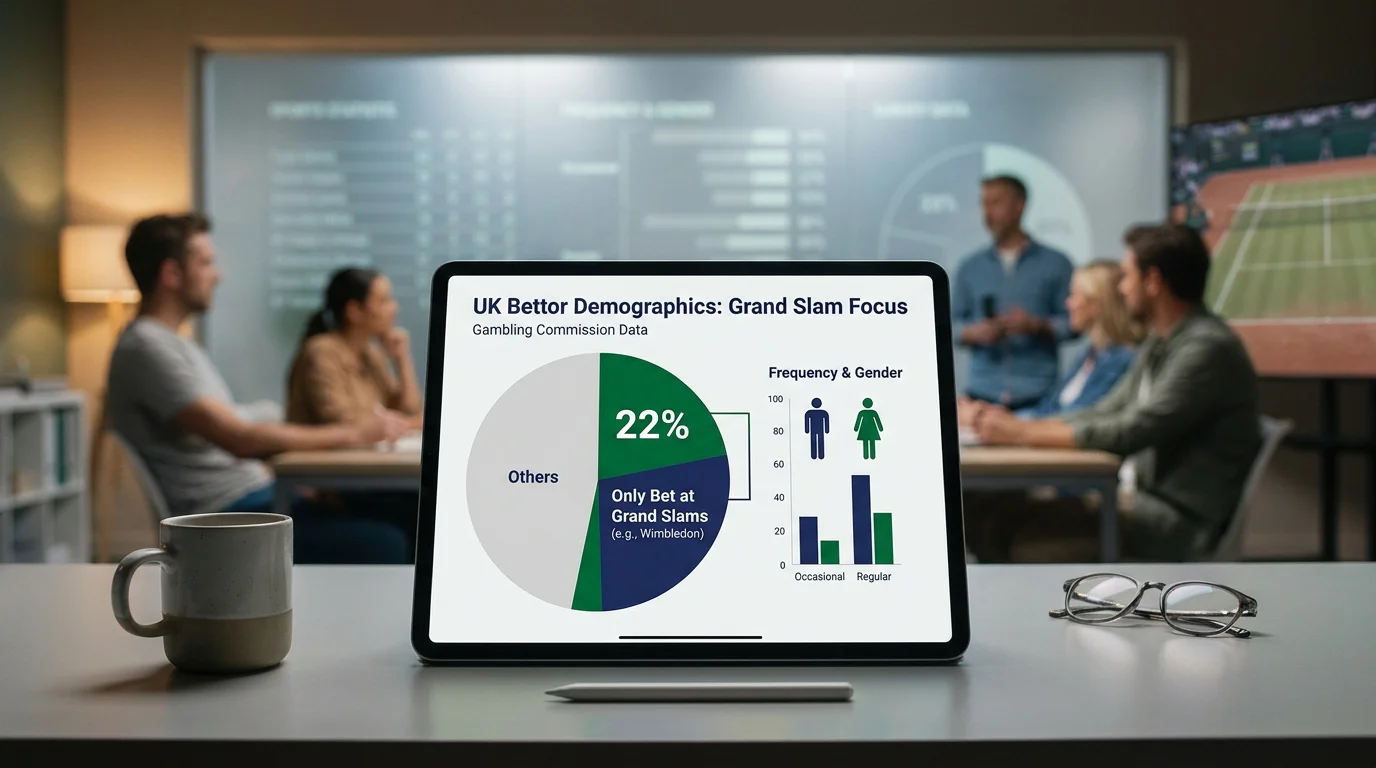
The frequency data on UK tennis betting is one of the most useful structural facts available for understanding the Wimbledon market. Only 7% of UK bettors follow tennis throughout the year. A further 22% bet exclusively on the four Grand Slam events. Taken together, this means that roughly three-quarters of the Wimbledon betting audience bets on the tournament without maintaining active engagement with the tennis betting market in the months between Grand Slams.
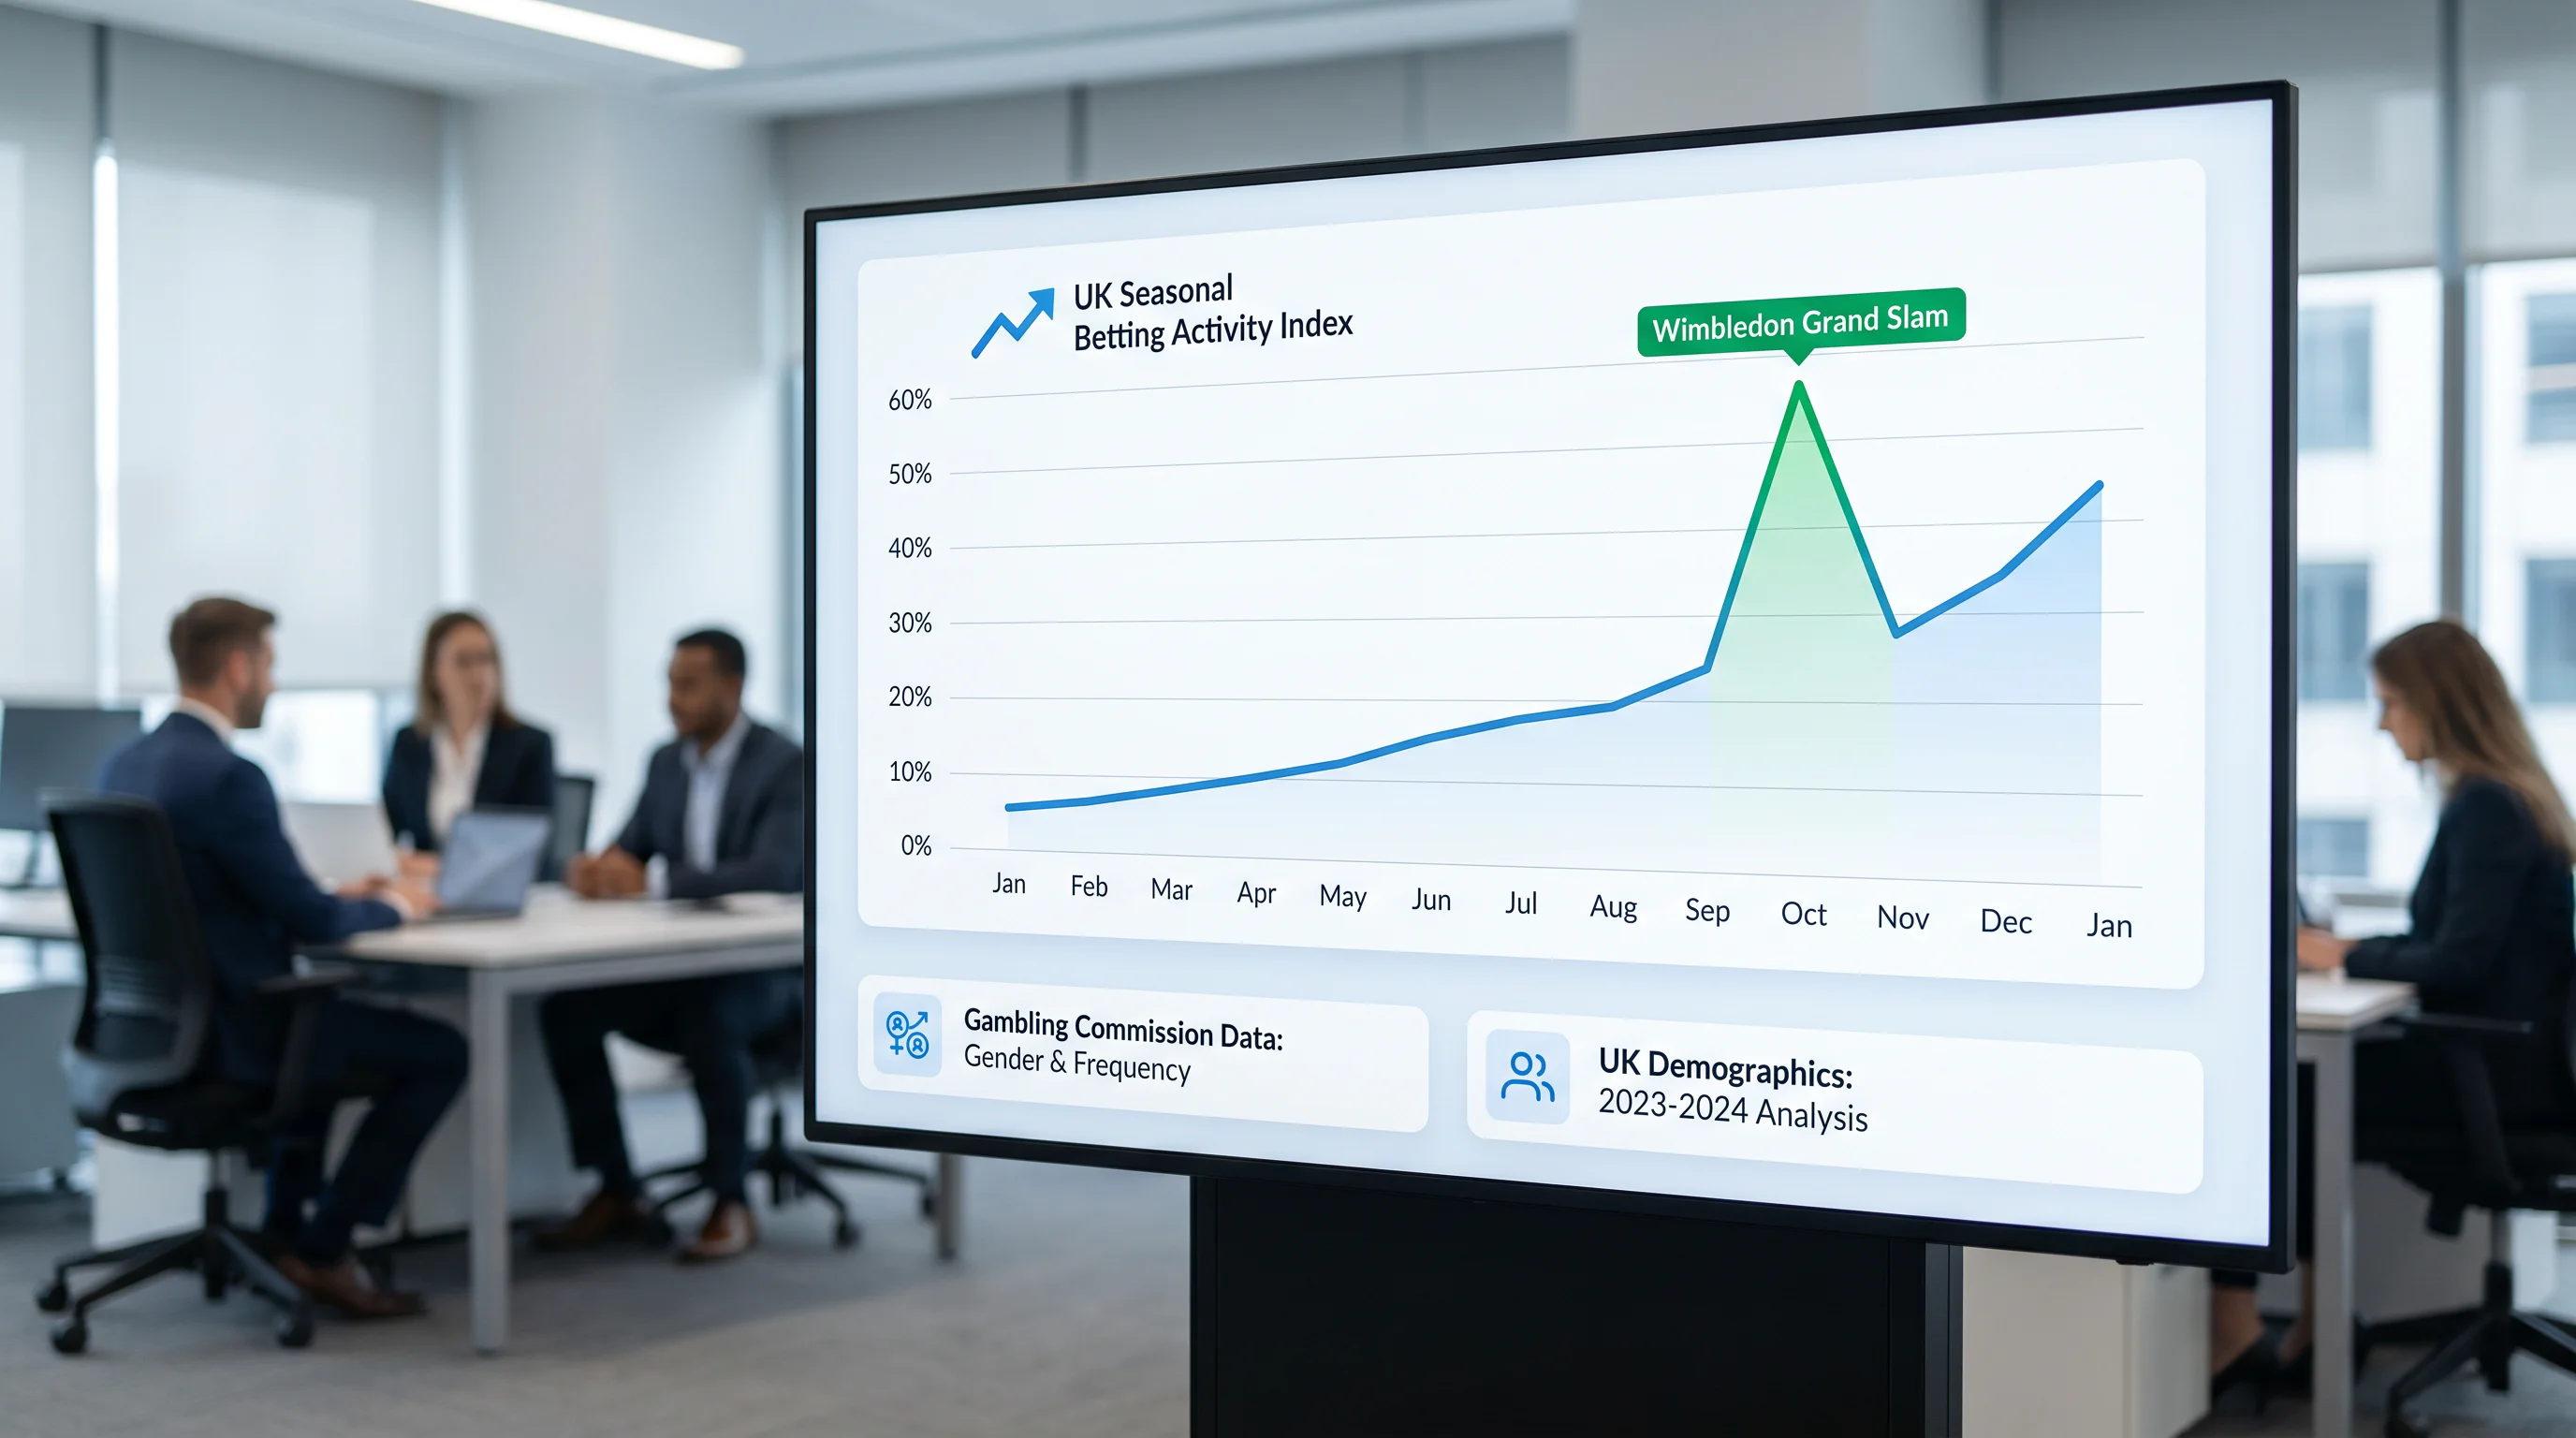
This seasonal pattern is not incidental to how Wimbledon markets are priced — it is central. The influx of once-or-four-times-a-year bettors creates a price environment that is, for a period of two to three weeks, distinct from the rest of the tennis betting calendar. Year-round tennis bettors — the 7% who track the ATP and WTA tours continuously — know each player’s recent results, current physical condition, coach changes, and technical adjustments in detail. The seasonal entrants do not. Their pricing input into the market reflects a more generalised view: ranking, past Wimbledon performance, and visible narrative (the British hope, the defending champion).
This creates a predictable pricing pattern. The selections favoured by narrative and ranking — top seeds, former champions, prominent domestic players — receive excess casual money that compresses their prices. The selections less visible to the seasonal audience — players whose recent grass-court form is strong but who lack prominent Wimbledon histories — are often priced at slight margins longer than their actual probability warrants. For the year-round tennis bettor who tracks these players across the grass-court swing, that pricing gap is the core value proposition at Wimbledon.
Casual vs. Core Wimbledon Bettor: Who They Are, Not What They Do
The distinction between casual and core Wimbledon bettors is demographic before it is behavioural. Understanding who each group is makes their behaviour in the market easier to interpret and more predictable to work around.
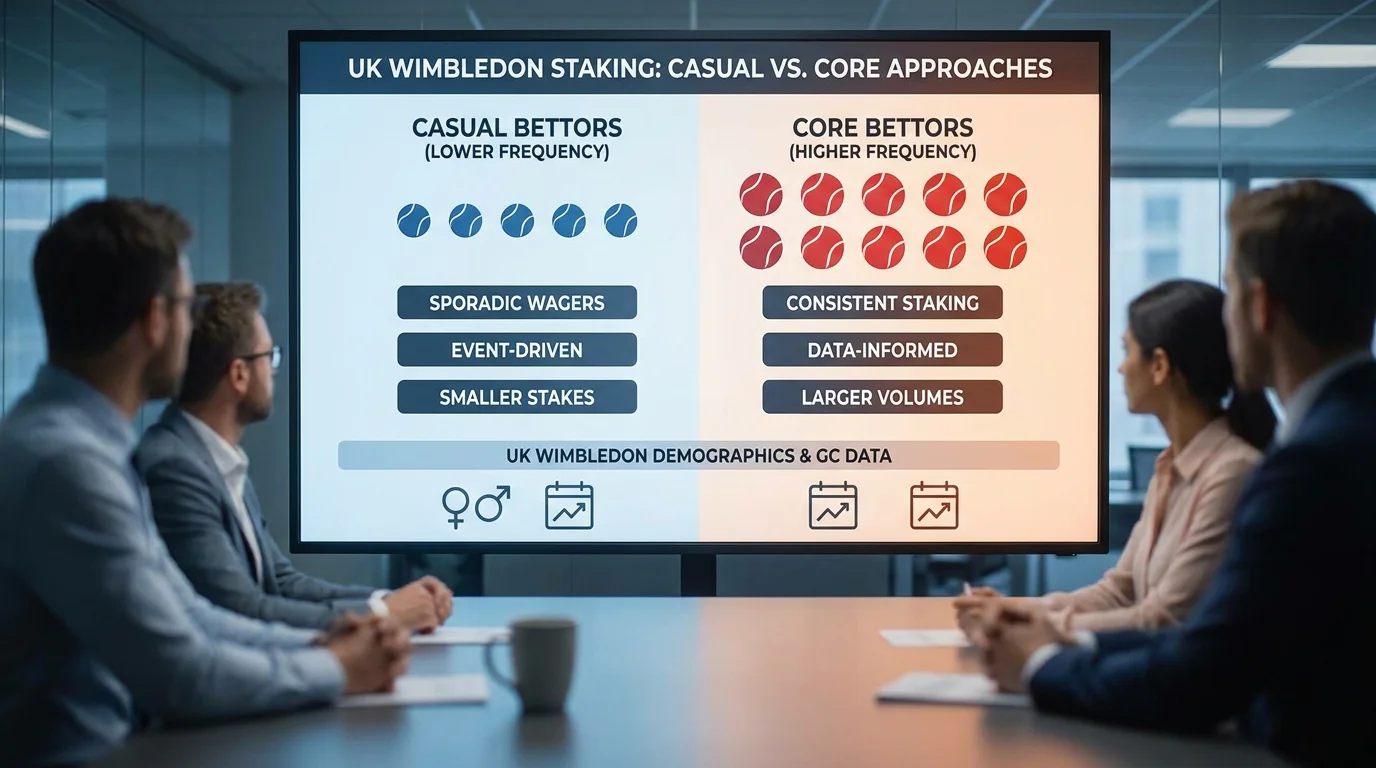
The casual Wimbledon bettor — numerically the majority — bets on Wimbledon as part of watching the tournament, not as a primary activity. They are more likely to be betting for the first time or one of very few times this year. Their stake is in the £5 to £50 range. Their selections are driven by what they have seen on the BBC or read in daily sports coverage. They are not shopping for odds across multiple operators, and they are not applying a systematic analytical framework. Their presence in the market increases volume and sustains operator margins on the most popular selections.
The core Wimbledon bettor — the 7% who bet on tennis year-round, plus the analytically-engaged subset of the 22% Grand Slam-only segment — approaches the tournament differently. They have already reviewed the draw, assessed the warm-up results, and identified one or two specific value opportunities before the first matches are played. They have operator accounts with the best current promotional offers for the tournament and have positioned their primary bets before the casual influx compresses the obvious prices on the first day of play. Their staking is more deliberate and often concentrated in fewer, better-researched selections.
The 13% participation rate among sports bettors planning to bet on Wimbledon represents both groups combined. The casual majority accounts for most of that number; the core minority accounts for most of the analytical market pressure. Understanding that Wimbledon markets are simultaneously serving these two very different groups — and that operators price to capture casual money while remaining competitive for professional money — is the frame within which every market decision at SW19 should be made.
The full picture of what this demographic reality means for specific betting decisions — staking habits, decision factors, and event comparisons — is at Wimbledon betting habits: what the 2025 YouGov survey reveals.
Articles
Created by the "bettingonwimbledontennis" editorial team.
